The End of the AI Trade. A Historic Week as the Stock Market Correction Deepens
Weekly Market Recap — Week ending 20 November 2026
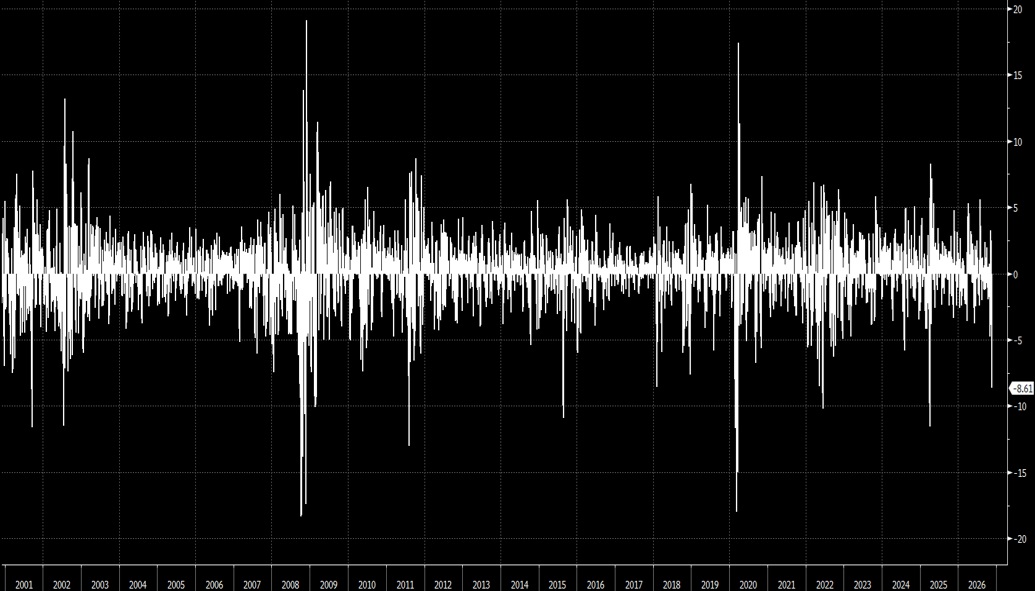
For four to six weeks, we’ve talked about the de-grossing. First hedge funds cut their AI exposure, then the CTAs followed. This week it was retail’s turn, and the result was one of the biggest weekly moves in decades. The S&P 500 fell 8.6%, a weekly drop that has happened fewer than ten times in the past 30-plus years. The Nasdaq fell 10%. The stock market correction is now official: the S&P 500 is down about 12% from its 6 October record, and the Nasdaq 100 is down about 20%, narrowly avoiding a bear-market close after its worst week since March 2020.

S&P 500 5days Returns.
This is the end of the AI trade, or at least of the AI capex momentum trade. After a huge rally in semiconductors and anything linked to AI capex, the climax came at the end of June. The reversal started two to three months ago. This week, it became a rout.
Macro Catalysts: The Anthropic IPO, Nvidia and the Missing Fed Put
1. The Anthropic IPO: you can lead a horse to water… The S&P was trading sideways until the Anthropic IPO. There’s a saying: you can lead a horse to water, but you can’t make it drink. For two to three months, the market has been questioning AI capex, and more precisely its financing. The IPO was pushed through just before Thanksgiving, priced at $83. The stock bounced twice above that level, pre-market and during the session, but the market had had enough of this trade and wasn’t buying it anymore. Bloomberg’s headlines tell the story: “Wall Street asks what can save AI trade after Anthropic wipeout.”
The smart money saw this coming. Elon Musk took SpaceX public in June, early enough to secure funding for AI capex for the months and years ahead. In the same week as the Anthropic IPO, he raised a further $40 billion-plus for chips. In 2027, I think many players will be short of funding, and the cost of money will be much higher. I’m now seriously questioning how OpenAI will do its IPO.
2. Nvidia: better numbers, wrong questions. Nvidia’s earnings were better. On valuation, you could argue it’s now cheap. But this isn’t about valuation. It’s about the CEO change and the question of circular funding: Nvidia investing in companies like Oracle that then buy Nvidia chips. The market isn’t trying to answer those questions yet. It’s simply selling. Bloomberg notes Nvidia had its worst week since 2008. Barclays takes the other side: Nvidia’s results reaffirmed that the capex cycle is intact. Their house view is that “the AI hype may have peaked, but not the investment race.”
3. Retail traders were destroyed. The macro was actually decent: retail sales were solid, and retailers like Walmart reported well. But from Thursday onwards, retail traders were hit hard. The hard-to-borrow retail basket fell about 17% on the week and high short-interest names about 20%. That means margin calls, and you could see it in the traditional retail safe haven too: gold fell 8–10%.

4. Where is the Fed put? Barclays makes the key point: beyond AI, the bigger problem for equities is that the Fed put appears to have disappeared. The Fed has been very hawkish, saying it won’t cut and will in fact hike more than expected because inflation isn’t coming down. This week:
- Governor Cook said the Fed “urgently needs to raise rates.”
- Philadelphia Fed’s Paulson said she’s open to consecutive hikes, though at a “deliberate” pace.
- Chicago Fed’s Goolsbee said “all options are on the table.”
- BNP Paribas now expects three consecutive 25bp hikes through March 2027.
Chair Warsh has also said the Fed will give the market less forward guidance. Without guidance, the market has to guess where the Fed put is. That probably means more pain until something breaks.
We could draw the parallel with December 2018, when equities fell about 20% before the Fed pivoted dovishly, sparking a sharp rally in early 2019. But here is the inconsistency: if equities are right to fear an AI slowdown, that should mean weaker growth and less need for the Fed to overtighten. Both narratives, a major AI slowdown and a much more hawkish Fed, can’t persist indefinitely.
Asset & Sector Performance: Total Carnage

The Russell 2000 fell about 7.5%, and the Stoxx 600 fell 5.8%, its worst week since April 2025, as the AI de-rating spread to Europe. The MSCI All Country World Index fell for seven straight sessions, its longest losing streak since September 2023. China’s AI-linked stocks have now lost a combined $1.7 trillion of market value since the end of June. The only market standing was India, seen as an AI loser and now benefiting from the reversal.
Year to date, the Nasdaq is now negative, the S&P 500 is only slightly up, and the Russell is up about 4%.

Commodities and crypto: going down the toilet. When you reduce exposure heading into year-end, you sell what you can, and you look for liquidity.
- Bitcoin fell below $60,000.
- Gold fell about 9% to around $3,540, its worst week since March.
- Silver fell about 15%.
- Copper fell more than 5% on the LME (around 10% on our charts), its lowest since April. Shanghai futures saw historic supply squeezes at the same time as the demand-driven selloff, a real market dislocation.
- WTI fell 5.2% to about $84.
Those who spent the summer producing 30–40-page presentations on the copper bull market have been totally wrong.
FX: The dollar has been very strong this year, and it edged up again this week (DXY +0.4% to 103.81). There’s a shortage of US dollars, a shortage of financing, and that’s forcing market participants to sell assets, from commodities to Bitcoin, to raise dollars. The Australian dollar moved a lot on commodities and housing concerns. The Mexican peso weakened past 19 per dollar, and the New Zealand dollar hit a six-year low.
Industries and sectors: In a sharp risk-off, only two assets normally hold up: Treasuries and the US dollar. The rest was carnage, led by solar, semiconductors and gold miners. Technology underperformed, in line with its beta of about 1.4–1.5. The supposedly defensive sectors did better: consumer staples, utilities and real estate all outperformed as yields fell. Goldman notes the selloff has broadened from an AI unwind to a broader growth downgrade, with cyclicals lagging defensives by 5 percentage points over the past ten days.

Biggest S&P 500 movers of the week:

The winners were a classic flight to defensives: food (Tyson, Hormel, General Mills), discount retail (TJX, Target, Tractor Supply), utilities (PG&E, Edison) and cybersecurity. Palo Alto, Okta and CrowdStrike held up as investors rotated into security software, helped by reports of CrowdStrike–Zscaler consolidation talks. The losers were the AI complex: Bloom Energy, Micron, Lumentum, Nvidia, Marvell and AMD, plus Freeport on copper, Intuit, and the crypto names (Robinhood, Coinbase). The median S&P 500 stock fell 6%. In the Nasdaq 100, Strategy (-25%), Nebius (-24%), CoreWeave (-21%) and Rocket Lab (-21%) led the losses.
Rates & Fed Expectations: The Flight to Safety
The flight to safety pushed the US 10-year down about 20bp to 4.95%, a big move that caught Treasury bears in a painful short squeeze. Germany’s 10-year fell about 9bp.
Fed expectations dropped sharply in a week. A December hike is still priced, at around 25bp for the 9 December meeting. Beyond that, the curve has come down a lot: through the end of next year, the market now prices roughly two hikes, about 25–30bp less than a week ago. With this carnage, the market is starting to say the end of AI capex could mean a struggling economy.

Volatility & Technicals: No Stock Market Correction Bottom Yet
VIX: It closed around 35–36 after trading near 40 intraday on Friday. Implied and realised volatility both jumped. What’s interesting is that the market wasn’t selling in panic. It was just selling, selling and selling, as if large orders were coming through alongside a lot of margin calls. I don’t think this is a sign that we’re bottoming. Many signals tell me the bottom isn’t here yet. It’s still de-grossing.
Positioning: Goldman makes the same point. Its Sentiment Indicator of equity positioning is still above average. Hedge fund net leverage has dropped to its lowest since April 2025, but US equity mutual funds and ETFs took in $150 billion over the past month, and futures positioning sits in the 82nd percentile versus the past ten years. Barclays notes long-only investors remain very long, “arguably the next shoe to drop.”
Nasdaq: A huge candle on Friday. I can’t give you a bottom level right now. Yes, it’s oversold, and yes, volume was massive, though Friday was options expiry, which inflated it.
S&P 500: The first level was 7,000, and we went straight through it. I don’t see real support I can identify. The RSI says oversold, but you can go much lower: back to the March levels around 6,500. If we go back to where this rally started in 2026, we’re talking another 10% from here.
Semiconductors (SOX): Same picture, with support 5–10% lower.
Nvidia: Last week we traded the bounce on $150 (150 to 160). That level has now broken. The next support is probably around $95, where a good friend of mine bought the lows during the 2025 correction.
JPMorgan: This is my check on whether this is only AI. It’s telling me it’s much more than AI. JPMorgan has broken below the trend that started in 2025. If that was the Trump trade, it suggests the economy may not do as well as expected, with possible regulation questions on top.

Gold: About a month ago, I was expecting a big move and looking at a 3-to-1 January put spread on GLD. We’re now close to the target level, and that worked well. Silver was a “don’t touch it if you’re long” chart: a confirmed downtrend that’s accelerating, with not much support before $35. Copper is a beautiful chart: support is probably around 5.20, another 6–8% lower. The Australian dollar could see another 5% correction to its trend support.
Overall, many assets could fall another 5–10%. I don’t have levels or signals yet. If you’ve been short, you’ve done very well. And watch out for the people suddenly claiming on social media that they were short Nvidia all along. They were nowhere to be seen for months.
Earnings Checkpoint: Valuation Reset, But Estimates Are Too High
Valuations have reset. S&P 500 forward P/E has dropped 25% this year to 16x, below its 30-year average. But the AI boom has lifted S&P 500 earnings about 25% above their 30-year trend. On trend earnings, the P/E still ranks in the 83rd percentile.
Estimates are still rising. Despite the selloff, sell-side analysts have kept raising 2027 S&P 500 EPS expectations, now around $428, which implies a P/E of about 16x. That’s back to the historical average, which isn’t actually that cheap. More importantly, there’s a mismatch between the buy side, which is already assuming lower earnings because AI financing will mean less capex, and the sell side. I think the banks will have to cut estimates quite quickly.

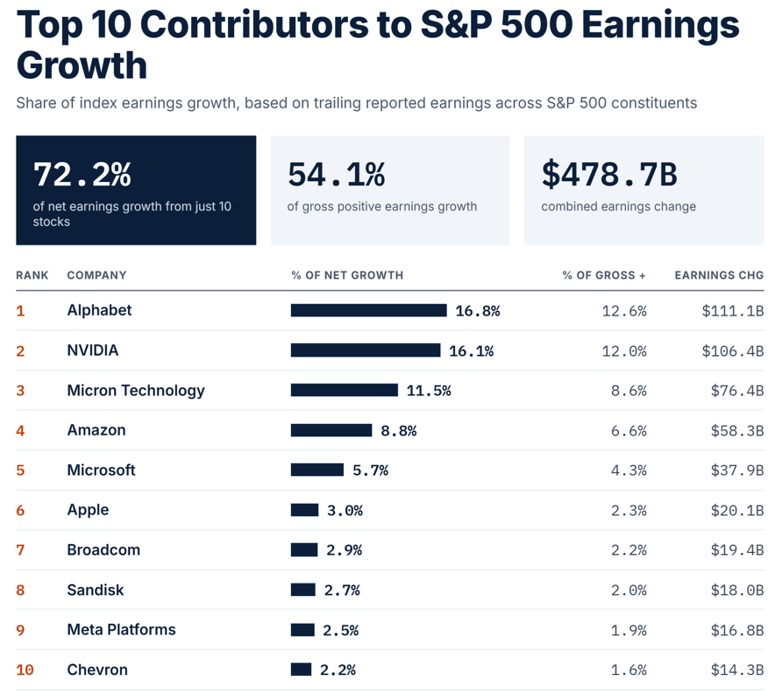
20207 S&P 500 EPSe
History offers some comfort. Every stock market correction feels different, but after 22 S&P 500 corrections of 10% since 1980, the index returned an average of 4% over the next 3 months, and was higher 73% of the time.
What would mark the bottom of this stock market correction? Goldman lists three conditions:
- News that increases confidence in AI-related earnings and monetisation
- A better macro backdrop, such as a dovish Fed signal
- A major decline in investor positioning
From our Trader’s call on Friday, we listed 3:
- Central banks act on liquidity. A central bank acknowledges there’s tight liquidity in the system, linked to the dollar shortage, and steps in to help “for real”.
- Something breaks, and someone steps in. An AI capex name or a neocloud runs into trouble, and a cash-rich buyer steps in. You gave Apple as an example, since it’s sitting on a lot of cash. But you also said it was “too soon, we are just at the start”: buyers have a reason to wait for lower prices.
- The Fed changes its tone. At the moment there’s no “Fed put”: the new chair has said he’ll be tough on inflation and give no forward guidance. You referred to the Barclays comment on this. Your view was that once he has to change his mind, “we wake up to the market gapping up”.
Right now, we don’t have the Fed put. Nvidia isn’t going to help: in previous episodes, its CEO would come out and say the financing was fine and AI capex was secure. That’s very different now. And there aren’t many earnings for the next two to three months.
The Week Ahead: PCE, a Short Week and the 2018 Playbook
This is a shortened week: US markets are closed on Thursday for Thanksgiving and close early on Friday.
- Mon 23-Nov: Flash PMIs (US, Eurozone, UK, Japan, Australia)
- Tue 24-Nov: Conference Board Consumer Confidence; German IFO
- Wed 25-Nov: Core PCE (cons. +0.3% m/m vs +0.3%); Q3 GDP; Durable Goods (cons. +0.6% vs +1.9%); Personal Income and Spending; FOMC Minutes; German GDP
- Thu 26-Nov: US Thanksgiving: markets closed; German GfK Consumer Confidence; Eurozone M3
- Fri 27-Nov: Early US close; Tokyo CPI (cons. 3.1% vs 2.8%); France CPI and GDP; Spain CPI and Retail Sales; Eurozone Consumer Confidence; China Industrial Profits
Also this week: ECB and BoE speakers are expected to reinforce rate-hike signals, and the ECB has warned that hedge fund positioning makes European sovereign debt more vulnerable to abrupt repricing.
PCE on Wednesday is the key release. It’s the last major inflation data point before the 9 December Fed meeting. What the market needs for a bounce is lower inflation and a Fed that turns.
The 2018 playbook. The closest stock market correction to this one may be 2018. In our midterm elections webinar, we looked at the scenarios. Most of the time, markets do fine after midterms, but not always. 2018 had the same configuration: a Fed saying inflation was a problem and it wouldn’t ease. The market sold off right up to the day before Christmas, then rallied. The big difference this time is the AI trade, which drove so much of 2026’s gains and is now reversing.
The options market expects big moves. The SPY weekly straddle is pricing about ±4.1% for this short week, and Monday alone has an expected move of about 2.4%, around 150–160 S&P points.
Trader’s Note: Hedge funds, then CTAs, now retail: the de-grossing has worked its way through the whole market. We’re getting closer to the end of it, but margin calls are still coming and the price action says the bottom isn’t in. We don’t have a Fed put, AI financing is still in question, and Nvidia no longer has a voice to calm the market. If you’re struggling, don’t chase and don’t let FOMO drive your trades. I haven’t done much over the past two weeks. I’m waiting for signals, and I don’t have a good entry point yet, long or short. Wednesday’s PCE and the Fed’s tone before 9 December are the catalysts to watch.
Stay Connected
Want to dive deeper or join the community?
🎓 Free webinar: How a prop trader builds his watchlist. Friday 5 December, 1:00pm London / 8:00am New York. Register here: Webinar
📧 Mentoring starting January 2027: I’m getting close to full capacity, so book soon: https://duponttrading.com/mentoring/
🎥 Access the 4×4 video series: https://duponttrading.com/4×4-course/
💬 Join the Discord: a free channel plus ~20 paid channels of trading insights: https://discord.com/invite/Yf42SgAx7f
For any questions or to join our mentoring sessions, email us at Greg 📩 Contact: greg@duponttrading.com
Have a good Trading Week!
Sub Section Title Here
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur. Excepteur sint occaecat cupidatat non proident, sunt in culpa qui officia deserunt mollit anim id est laborum.
Related Articles
Nvidia Drama: A CEO Exit, Yields Back Above 5% and Nvidia Earnings Ahead
Weekly Market Recap — Week ending 13 November 2026 This week was all…
VIEW POST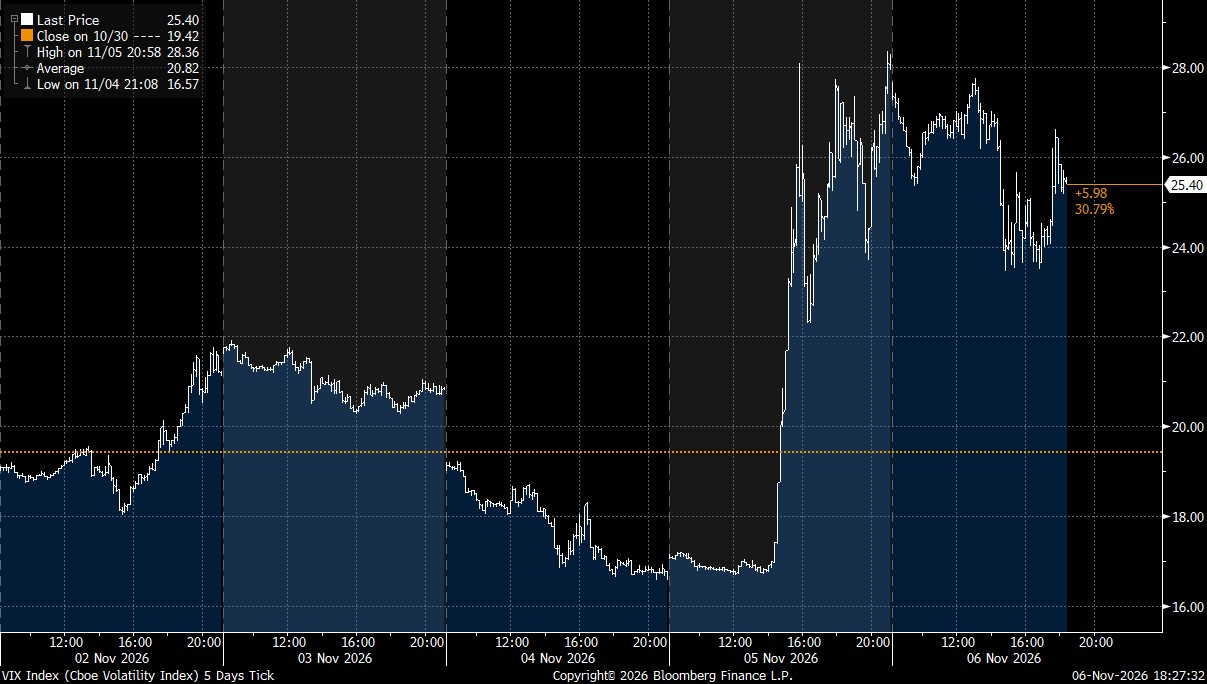
Midterms Trigger an AI Rout, Oil Plunges 13% and the VIX Hits 26
Weekly Market Recap. Week ending 6 November 2026 Midterms usually act as a…
VIEW POSTTHIS POST

LEARN ONLINE TRADING TODAY. THE PROFESSIONAL WAY.
Let us solve the problem and confusion around trading and finance management, the right way.
ACCESS FREE LECTURESUBSCRIBE
TO OUR BLOG
To receive opinions, market research, and data analysis in the Financial Markets
ABOUT
DUPONT TRADING
As a Professional Trader/Portfolio Manager/Hedge Fund Manager for almost 20 years, I know that learning how to Trade/Invest is a non-ending learning curve. This adventure is extremely exciting but needs to be ridden carefully.
In January 2018 after receiving many requests, I decided to start my own mentoring activities.
In October 2019, I launched the 4×4 Video Series to help Investors profitably manage their portfolios. By sharing my ideas/experiences and offering education through the 4×4 Video Series, I hope I can help you becoming a better investor.
Students
Testimonials

T. (France)
LEARN ONLINE TRADING TODAY. THE PROFESSIONAL WAY.
Let us solve the problem and confusion around trading and finance management, the right way.
Reader Interactions