Hedge Funds Crushed: A Historic Unwind, a Violent AI Rotation and $117 Oil
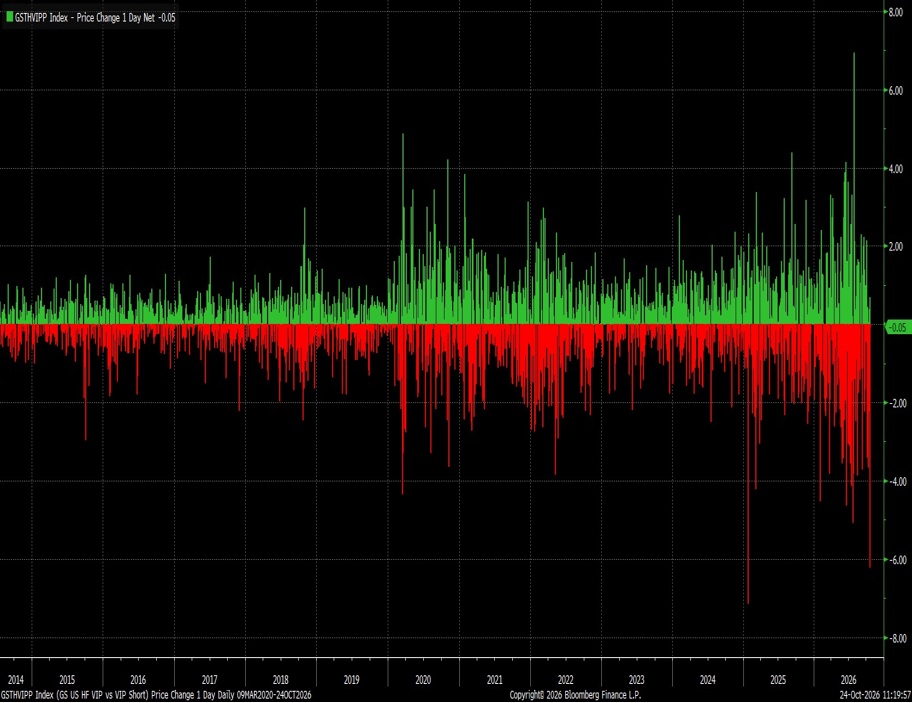
On the surface, it was a quiet week: the S&P 500 finished only slightly lower. Underneath, it was anything but. A hedge fund unwind on Thursday, right after Meta and Tesla reported, sent Goldman Sachs’ basket of the most popular hedge fund longs versus shorts down 4.2% in a single day. In the past decade, only DeepSeek Monday (January 2025) and the COVID crash (March 2020) come close.

The result was one of the sharpest rotations of the year. Out went the AI capex winners: semis, chip equipment, electricity and data-centre builders. In came software, cybersecurity and the laggards, with the Russell 2000 up 2% while the Nasdaq 100 fell 1.9%. All of this happened against a backdrop of oil pushing back to war-time highs, the 10-year Treasury slipping below 5%, and the VIX holding around 20 with the midterms ten days away.

Macro Catalysts: Capex, Oil and France
1. The AI capex financing question. This was the trigger. Meta and Tesla reported on Wednesday after the close.
- Tesla raised questions about how much capex it will spend going forward, and therefore how much AI it needs.
- Meta was the more interesting one. Its CEO said everyone is competing for compute by building data centres, but the message the market heard was that there won’t be capital for everyone. The industry clearly needs huge capex over the next three to five years. The problem is that not every company will be able to fund it.
CoreWeave is the poster child: its bonds yield around 15%, and the stock has fallen alongside them. There’s also a domino effect worth understanding. Rumoured valuations for the leading AI labs have reportedly come down a lot, from talk of $2 trillion to $1–1.5 trillion. Lower valuations mean less equity, which means less collateral to borrow against, which means less capex. It works like remortgaging a house: if your house falls from £1.5 million to £1 million, you can’t borrow as much against it.
Not everyone is bearish. Goldman Sachs upgraded CoreWeave to Buy this week, and Barclays’ macro team cautions against extrapolating the credit stress in parts of the neocloud space to the whole AI capex cycle. Q3 results from the major upstream AI providers have so far beaten expectations. But the headlines tell you where sentiment sits: Apollo’s Torsten Slok argued AI has delivered “zero payoff” outside of tech, Goldman cut its 12-month KOSPI target by 25%, and Bloomberg described a “total meltdown” in the riskiest debt.
2. Oil is the concern. Front-month Brent rose about 6% this week to around $117 a barrel, at or near its war-time highs, and WTI pushed to new recent highs on Friday. What’s changed is how markets react. Earlier this year, higher oil triggered inflation fears. Now it is triggering growth fears, which is why yields fell even as oil rose. Higher oil is colliding with still-resilient demand from the AI investment cycle, keeping pressure on credit markets and tilting central banks hawkish. As they put it, “something has to give.”
Oil is also driving cost-of-living protests in France and parts of Italy, and US consumer sentiment slipped to a five-month low. In the UK, war-driven energy costs pushed inflation to an almost one-year high.
3. France and contagion risk. Especially for those of us trading Europe, French bonds remain a concern. The OAT–Bund spread widened to almost 175bp this week. That matters because it puts pressure on European banks, and with Europe there is always a risk of contagion. So far the market isn’t panicking: EUR/USD was broadly flat on the week. After Friday’s close, Moody’s kept France’s rating unchanged with a negative outlook. You can argue rating agencies are very often late. I’ll keep monitoring EUR/USD, bonds and equities for signs of contagion.
Asset & Sector Performance: The Hedge Fund Unwind Drives a Massive Rotation
The headline indices barely moved, but the rotation underneath was huge:
- US: The S&P 500 slipped slightly and the Nasdaq 100 fell 1.9%, while the Russell 2000 rose about 2%. A couple of weeks ago, I flagged that the Russell had underperformed the S&P by 8–10% since September because of financing risk. This week, that trade reversed.
- Asia: Japan’s Nikkei fell 3.4%, dragged down by a plunge in SoftBank, and Korea was weak again. China’s CSI 300 entered a bear market, down 20% from its June highs.
- Europe: The Stoxx 600 fell about 1.4%, the FTSE 100 0.7% and the DAX 0.6%. Switzerland was the bright spot: the SMI is up 4.6% in October as investors rotate into defensives.
- FX and commodities: The Australian and Canadian dollars moved a lot. Gold fell about 4% and is now below $4,000. Crypto was under pressure, and that’s an understatement.
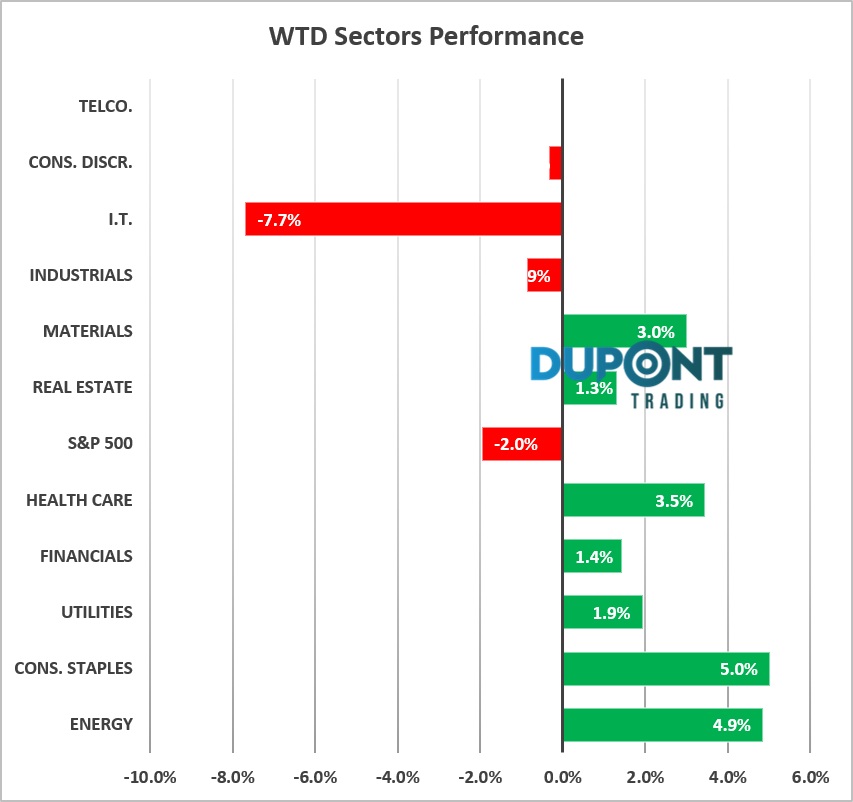
Industries: winners and losers swapped places. Software and cybersecurity, which had been crushed on fears that AI would destroy their businesses, rallied hard on Thursday and Friday. The big AI winners (semis, chip equipment, electricity, data-centre builders) came down. Chipmakers posted eight straight down sessions, their longest losing streak since 2008.
Sectors: Telecoms were down big. Meta was under pressure, and Starlink keeps squeezing the operators. If you run Porter’s Five Forces, as we do in the mentoring sessions, Starlink is a classic new entrant taking market share from Verizon, AT&T and T-Mobile. Industrials also struggled on disappointing earnings. That’s a sign the market is pricing more of the left tail: that high yields and high inflation will hurt the economy, especially if AI capex slows because financing is stretched.
Biggest S&P 500 movers of the week:

The table shows the hedge fund unwind in action. Software and cyber led the gainers: CrowdStrike, Roper, ServiceNow (+12%) and Gartner (+12%). AI infrastructure filled the losers: Lam Research, KLA (-12%), GE Vernova (-12%), Quanta, EMCOR (-10%) and NRG (-11%). AT&T (-11%) represents the telecom pain. In the Nasdaq 100, Thomson Reuters (+13%), Palo Alto Networks (+11%) and Workday (+10%) joined the software rally, while CoreWeave (-12%) and Astera Labs (-10%) were among the worst.
Rates & Fed Expectations: Out of Panic Mode
The US 10-year fell about 8bp on the week and dipped below 5% for the first time since the Fed hiked in September. A couple of weeks ago it was at 5.35%. We’re no longer in panic mode in the bond sell-off. Inflation is still a concern, but less than before. The market is now pricing a different risk: that AI financing pressure leads to a slowdown relative to expectations. Bonds are working as a safe haven again.
Fed expectations: The Fed meets on Wednesday and is expected to hold. Markets price about 3bp of additional tightening for this meeting and a 25bp hike in December (about +21bp priced), with more priced for January 2027.
Volatility & Technicals: The Midterm Vol Call Is Paying Off
VIX: I pushed this idea two to three weeks ago during the midterm election webinar: that we could see a rise in volatility into the midterms. That’s exactly what has happened. Maybe I’ve been lucky, but the VIX is now around 20, and the VIX call spreads I talked about have paid off. Interestingly, this week wasn’t about tail hedging. The CBOE SKEW index peaked about ten days ago, when the market was scared about the left tail. This week was about a hedge fund unwind: de-grossing and rotation. If you were defensive and long non-AI (software, cyber) against a short in AI or the Nasdaq, you had a very good week.
Positioning: After this hedge fund unwind, Goldman’s Prime Services data shows fundamental hedge fund net leverage close to five-year lows, while gross leverage remains above the 90th percentile of the past five years. That leaves room for more de-grossing. Retail is stepping back too: retail trading now accounts for about 9% of US equity volume, down from 15% late last year and near its lowest since 2020.
Technicals:
- Real estate (XLRE): We flagged the channel breakout a few weeks ago. With yields no longer rising, XLRE is up 4–5% from that level.
- Energy (XLE): It was very strong on Friday, with names pushing higher in both the US and Europe. That tells you the market is convinced oil stays high for longer.
- Gold: Now below $4,000, with the key support around $3,970. Everyone is watching that level. We saw a lot of cross-asset portfolio rotation on Thursday and Friday.
- Russell 2000: It bounced on old resistance, now support, but it is still in its downtrend. Nothing has broken yet.
- Nasdaq: It broke the uptrend that started in early April, so there’s a chance it goes lower.
- Magnificent 7: Same story. The trend has broken, and the next support suggests roughly another 3% downside. That matters with the hyperscalers reporting this week.
Since Meta and Tesla reported on Wednesday evening, the S&P 500 has lost roughly 100–150 points.
Earnings Checkpoint: Good Earnings, Weak Sales
With about a quarter of S&P 500 companies reported:
- Earnings surprise: around 5% on average. That’s roughly in line with history once you set aside the exceptional last two quarters.
- Sales surprise: only about 1%. As we’ve discussed in detail in the Discord community, that’s the more telling number. The quality of the beats isn’t as strong as before.
- Measure: 57% of companies have beaten EPS by more than one standard deviation, versus 69% in Q2. On revenue, 40% have beaten and 18% have missed.
Growth is holding up with little evidence of guidance cuts, but decent earnings are struggling to lift equities, with oil acting as a cap.
This is the biggest earnings week of the season:
- Microsoft, Alphabet and Amazon. The hyperscalers will show just how much AI compute demand they are seeing. Alphabet and Amazon report Thursday after the close, the day after the FOMC. Implied moves range from about 4% to 7%.
- Also reporting: Intel, Visa, Mastercard, Verizon, T-Mobile, Coca-Cola, Starbucks, S&P Global, Boeing, Eli Lilly, Merck, AbbVie, Chevron and ExxonMobil.
Coming after Meta’s capex comments, the hyperscalers are the real test of whether AI spending is slowing.

The Week Ahead: Fed, ECB, BoJ and the Hyperscalers
- Mon 26-Oct: Chicago Fed National Activity Index; German IFO; Japan Leading Index
- Tue 27-Oct: Durable Goods; Conference Board Consumer Confidence; New Home Sales; China Industrial Profits
- Wed 28-Oct: FOMC decision (hold expected); Wholesale Inventories; German GfK Consumer Confidence
- Thu 29-Oct: PCE (core cons. 3.1% vs 3.0%); Q3 GDP (cons. 3.0% vs 2.2%); Personal Income; ECB decision; Eurozone Consumer Confidence; 7-year Treasury auction ($44bn); Alphabet and Amazon after the close
- Fri 30-Oct: BoJ decision (cons. hold at 1.25%); Chicago PMI; Eurozone GDP and Unemployment; CPI for Germany, France, Spain, Italy and Japan; Japan Jobless Rate, Retail Sales and Industrial Production; G20 Foreign Ministers Meeting
- Sat 31-Oct: China PMIs
FOMC: watch the day itself. Since Chair Warsh took charge, stocks have fallen on the day of each of the last three FOMC meetings. That’s worth keeping in mind on Wednesday.
Also on the radar:
- Elections in Brazil and Israel
- UK Prime Minister Andy Burnham’s first budget, with gilts watching fiscal credibility closely
- China’s Fifth Plenum
- End-of-month bond supply, which could pressure yields
The SPY weekly straddle stands at about ±1.8%, much higher than two to three weeks ago.
And ten days out: the midterms (3 November). Uncertainty is rising, with the war in the Middle East not ending and the Trump administration saying it will strike Iran again just after the midterms. Barclays notes that history suggests the vote itself tends to act as a clearing event for markets.
Trader’s Note: When a hedge fund unwind delivers one of the worst days in a decade while the S&P barely moves, the message is rotation, not crash. The crowded AI capex winners are being sold to fund the laggards. That can last longer than people expect, especially with gross leverage still elevated and the Nasdaq and the Mag 7 having broken their trends. This week’s FOMC and hyperscaler earnings, landing on back-to-back days, decide whether the rotation becomes a broader de-rating. Stay balanced between AI and non-AI, respect the $3,970 gold level, and don’t fight a VIX at 20 heading into the midterms.
Stay Connected
Want to dive deeper or join the community?
🤖 AI webinar — 7 November, 1:00pm London. How I use AI every day for my trading, my infrastructure and education, with real trading examples and setups. Free for paid Discord members, or register for $60: https://duponttrading.com/how-i-use-ai-every-day-as-a-trader/
🗣️ Weekly community call on Discord (members only), to share ideas, ask questions and learn how to build your own trading infrastructure.
📧 Book mentoring for Q4 2026: https://duponttrading.com/mentoring/
🎥 Access the 4×4 video series: https://duponttrading.com/4×4-course/
💬 Join the Discord: 30 channels of trading insights: https://discord.com/invite/Yf42SgAx7f
For any questions or to join our mentoring sessions, email us at Greg 📩 Contact: greg@duponttrading.com
Have a good Trading Week!
Sub Section Title Here
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur. Excepteur sint occaecat cupidatat non proident, sunt in culpa qui officia deserunt mollit anim id est laborum.
THIS POST

LEARN ONLINE TRADING TODAY. THE PROFESSIONAL WAY.
Let us solve the problem and confusion around trading and finance management, the right way.
ACCESS FREE LECTURESUBSCRIBE
TO OUR BLOG
To receive opinions, market research, and data analysis in the Financial Markets
ABOUT
DUPONT TRADING
As a Professional Trader/Portfolio Manager/Hedge Fund Manager for almost 20 years, I know that learning how to Trade/Invest is a non-ending learning curve. This adventure is extremely exciting but needs to be ridden carefully.
In January 2018 after receiving many requests, I decided to start my own mentoring activities.
In October 2019, I launched the 4×4 Video Series to help Investors profitably manage their portfolios. By sharing my ideas/experiences and offering education through the 4×4 Video Series, I hope I can help you becoming a better investor.
Students
Testimonials

T. (France)
LEARN ONLINE TRADING TODAY. THE PROFESSIONAL WAY.
Let us solve the problem and confusion around trading and finance management, the right way.
Reader Interactions