France Blows Out, Payrolls Flop, 30-Year Hits 5.63%: Only Tech Holds the Line
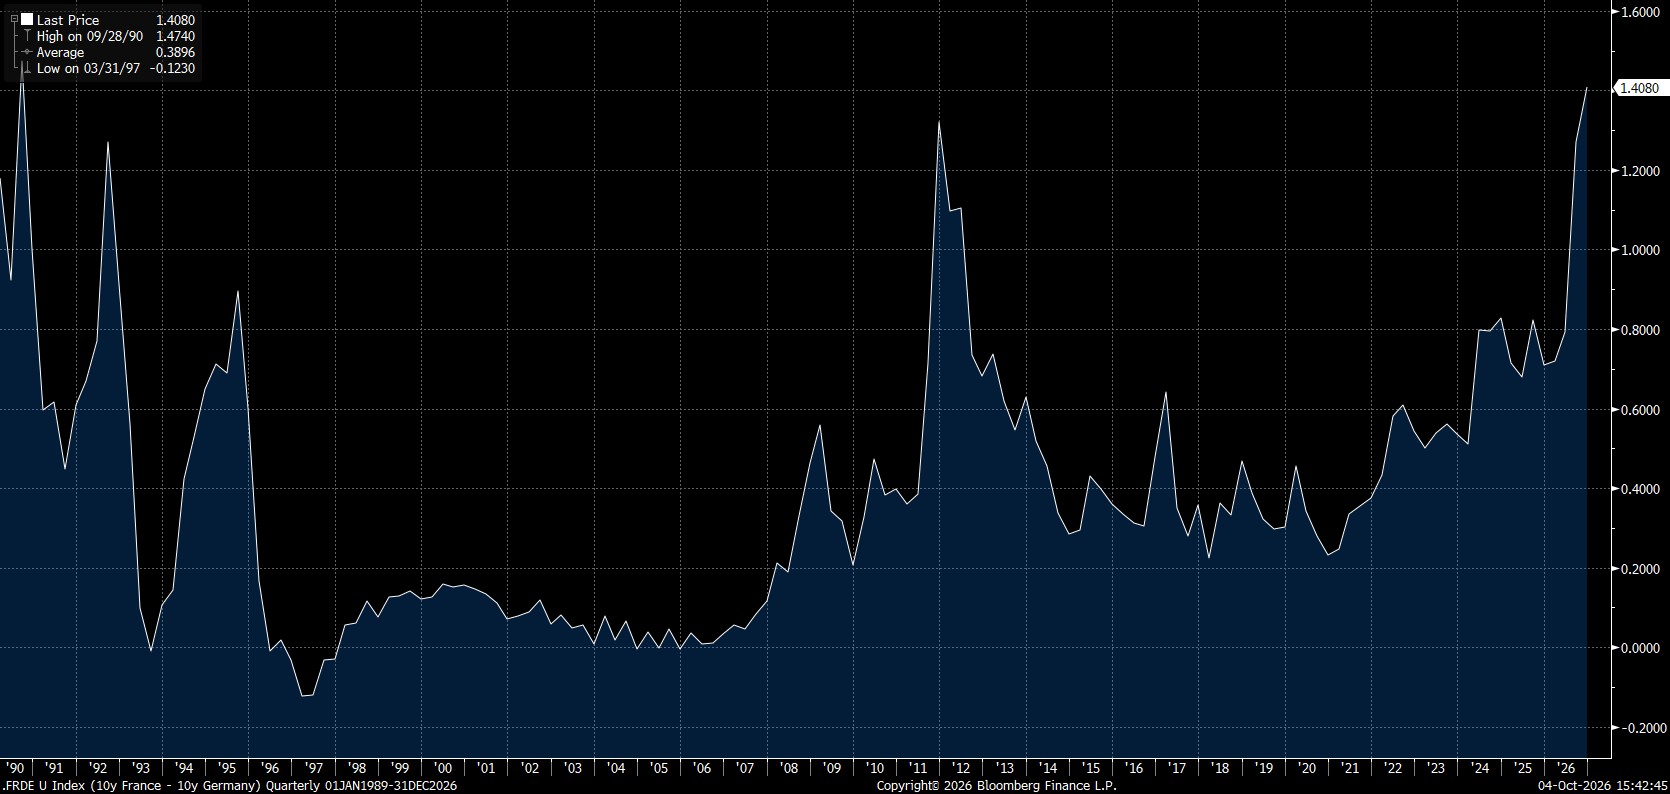
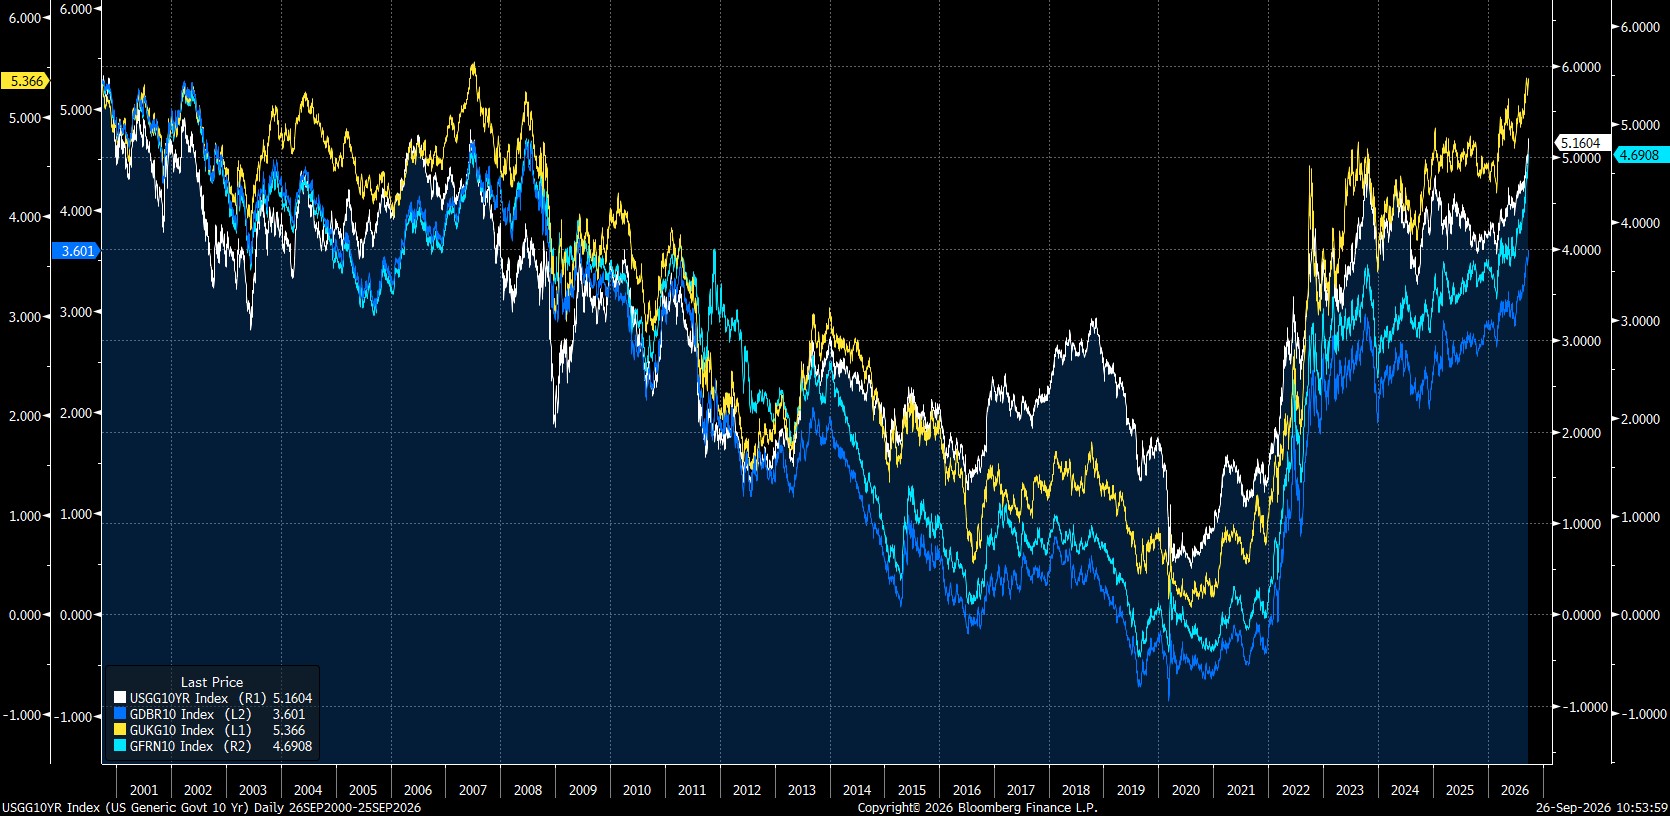
Another week of big moves for bonds, and a French bond spread crisis at the centre of it. The French–German 10-year spread blew out to almost 160bp on Friday, its widest since the euro sovereign crisis. Across the Atlantic, the US 30-year yield touched 5.63%, its highest since 2002, and the 10-year hit roughly 5.29%, near its highest since 2007.

France 10y vs Germany 10 y since early September.

France 10y vs Germany 10 y since 1990.
On the surface, US stocks barely flinched. The S&P 500 finished the week roughly flat (-0.25%), the Nasdaq edged up about 0.5%, and the VIX actually fell to around 15. Underneath, it was a very different market. Only about one in four S&P 500 stocks is trading above its 50-day moving average, new 52-week lows outnumbered new highs by almost 2-to-1 on Friday, and on a sector basis, it was almost entirely about Tech.
Macro Catalysts: A Hot Economy, a Cold Jobs Report
The data told a contradictory story all week.
Growth is resilient. Q2 GDP was revised up to +2.2% annualised (vs +1.5% expected), driven by consumption growing 3.8%. August personal spending jumped 0.9%, the biggest monthly gain in over a year. Manufacturing stayed in expansion for a ninth straight month: ISM Manufacturing printed 54.5 (vs 55.0 expected), with New Orders at 55.3. The Chicago PMI was the week’s biggest upside surprise, surging to 58.8 from 47.1.
But the labour market is softening. Friday’s September payrolls came in at just +29,000, missing every estimate in Bloomberg’s survey (median +90,000). August was revised down to +133,000 from +162,000, taking the two-month net revision to -60,000. The unemployment rate rose to 4.2% (partly reflecting participation ticking up to 61.8%). Average hourly earnings rose only 0.1% on the month and 3.0% on the year, and the 3-month average payroll gain fell to 51,000. JOLTS job openings dropped to a five-month low of 7.08 million.
Not everything was weak: initial jobless claims fell to 197,000, the lowest since July, and continuing claims dropped to 1.70 million, a three-year low. ADP also beat at +90,000. That’s what made Friday’s miss so jarring.
The consumer is feeling the squeeze. Conference Board Consumer Confidence collapsed to 81.9 (vs 89.0 expected), with the Expectations index at 63.6, approaching levels historically associated with recession concerns. Personal income rose just 0.2% (vs 0.5% expected), so households are spending more than they earn. Prices have now outpaced wages for five consecutive months.
Inflation is sticky under the hood. Core PCE surprised to the downside at 3.0% year on year (vs 3.3% expected), and headline came in at 3.4% (vs 3.7%). But the Fed’s favourite sub-component, supercore PCE (services ex-housing), re-accelerated to +0.4% on the month. ISM Prices Paid jumped to 77.9 from 71.1, well above the 73.0 estimate, a clear sign of resurgent input-cost pressure.
Oil stayed elevated but volatile. Brent spiked to $105.28 on Monday amid the US-Iran standoff, then pulled back to around $102 as the Trump administration released oil from strategic reserves and reports pointed to improving crude flows through the Persian Gulf. WTI settled near $91. Refined products like diesel remain tight, keeping the inflation narrative alive.
France: “Le Spread.” Barclays describes France as having moved into crisis mode. Higher inflation, persistent fiscal slippage, political uncertainty and a record 2027 funding programme are all pushing the French risk premium higher. The government unveiled its FY27 budget this week, targeting a 5.0% of GDP deficit, only a 0.4pt improvement on current levels. Parliamentary debates start on 13 October, leaving roughly 70 days to get it passed. Market stress itself may help the budget pass, since no major party has much to gain from a full-blown financial crisis ahead of next year’s presidential election. French 10-year yields rose 27bp on the week, versus +11bp in the US, and German 10-year yields actually fell 14bp.
Asset & Sector Performance: Stocks Flat, Strong Dollar, Gold Down
US indices were essentially flat: S&P 500 -0.25%, Nasdaq +0.46%. September closed as the S&P 500’s worst month since June. Europe fared worse. The Stoxx 600 fell 1.1% to a three-month low, posting its worst month since March in September (-2.5%), and the FTSE 100 was the weakest major index, down about 2.1%. Japan’s Nikkei was again the standout, up roughly 3%.
The US dollar climbed about 1% to a two-month high, the euro hit its weakest level in 16 months, and USD/JPY pushed to around 158 after the Bank of Japan’s September meeting summary gave no clear signal of an October hike. Gold fell about 3.4% on the week, with silver and the gold miners at the very bottom of the industry leaderboard.

Sectors: on a weekly basis, it was mostly about Tech. Technology (+1.8%), Energy (+1.3%) and Utilities (+0.8%) were the only sectors in the green. Everything else was down: Health Care (-2.6%), Financials (-2.3%), Telecoms (-2.3%), Consumer Staples (-1.9%), Materials (-1.8%) and Real Estate (-1.8%). Financials have been hit particularly hard by the rate move, with Bloomberg noting the sector just suffered its second-worst September in 15 years. Year to date, Energy (+41%) and Tech (+39%) remain miles ahead of the S&P 500 (+13%). Across industries, there were not many winners: cybersecurity, semiconductors and cloud led, while silver, gold miners, solar, pharma and airlines lagged.

Biggest S&P 500 movers of the week:

The cruise lines surged on strong forward booking data and easing fuel-cost concerns. Synopsys, Coherent and Lumentum were swept up in a broad semiconductor equipment and photonics rally. In the Nasdaq 100, Applied Materials, Lam Research, KLA, Teradyne and ASML all gained 7–13%, helped by read-throughs from Micron’s blowout quarter, while cybersecurity names Palo Alto Networks and CrowdStrike added about 7%. On the downside, FICO’s 23% drop was the steepest in the S&P 500. Biotech struggled (Alnylam, Regeneron, Vertex), and storage names Western Digital and Seagate fell sharply despite the broader semis rally.
Rates & Fed Expectations: The Long End Takes the Pain
The bond rout was global, but concentrated at the long end:

Beyond the 10-year, the US 30-year hit a 24-year high of 5.63% on Wednesday after the strong spending data, and UK 30-year gilt yields briefly breached 6%.
Fed expectations are coming down. Following September’s 25bp hike, fed funds futures now price roughly one more hike by year-end, and expectations eased through the week. After Friday’s payrolls miss, money markets priced less than a 40% chance of a hike at the 28–29 October meeting, down sharply from last week. NY Fed President Williams said one more hike “late this year” may be appropriate but that there is no urgency, and Cleveland Fed President Hammack noted policymakers have plenty of time to assess the data. Further out, December 2027 fed funds futures still sit about 84bp above where they were at the end of August, so the bigger hawkish repricing hasn’t unwound.
What this means for equities: Rrising rates are now starting to bite. Equity risk premia have compressed as bond yields rose, challenging the “there is no alternative” case for stocks, and equity sensitivity to rates is increasing. If the rates sell-off stabilises (ideally with oil moderating), equities should find support. If not, the typical year-end rally may not play out.
Volatility & Technicals: A Calm VIX on a Narrowing Base
The VIX ended the week at 15.31, down 1.4 points, despite the bond turmoil. The SPY weekly straddle is pricing roughly ±1.2% for next week.
Breadth is very poor. Data shows only 24.7% of S&P 500 members trading above their 50-day moving average as of Friday’s close, and just 45.7% above their 200-day, meaning more than half the index is in a longer-term downtrend while the index sits less than 1% from its August record. Decliners beat advancers in three of the five sessions, with Wednesday the worst day (-263 net decliners), and new 52-week lows (20) outnumbered new highs (11) on Friday. The share of stocks below their 200-day average is approaching the March lows, with nearly half of MSCI World constituents trading below it.

S&P 500 Stocks trading above their 50-day moving average.
Relative performance: Looking at US sector relative-performance charts, only Tech looks good. Consumer Discretionary, Staples, Real Estate, Utilities and Communication Services remain in clear relative downtrends.
Two views on what comes next. The contrarian case says narrow leadership sets up a catch-up rally once rate pressure eases. The bear case says deteriorating breadth plus surging yields is a significant warning signal.
Earnings Checkpoint: Micron Delivers, Delta Up Next
Micron delivered a blowout quarter, and the stock rose about 3% on Thursday, taking its year-to-date gain to roughly 285%. The read-through powered the semiconductor equipment complex all week.
Next week’s earnings calendar is relatively light, but there are a few names worth watching:
– **Tue:** RPM International, Penguin Solutions, Neogen
– **Wed:** Applied Digital, Levi Strauss, Richardson Electronics, RGP
– **Thu:** PepsiCo, Tilray, Helen of Troy, NovaGold, Byrna
– **Fri:** Delta Air Lines
Options markets are pricing the biggest expected moves in a gold miner and an AI data-center builder on this calendar, NovaGold and Applied Digital fit that description. Delta on Friday gives the first read on the airlines and fuel costs, and the Q3 earnings season proper kicks off with the banks shortly after.
The Week Ahead: FOMC Minutes, Services ISM and Long-End Auctions
– Mon 5-Oct: Services & Composite PMIs; ISM Services (cons. 55 vs 55.4); Eurozone PPI
– Tue 6-Oct: Trade Balance (cons. -$83.3bn vs -$88.6bn); 3-year Treasury auction ($58bn); Fed’s Williams, Bowman and Schmid speak
– Wed 7-Oct: FOMC Minutes from the September hike meeting; 10-year reopening auction ($39bn); Japan Labour Cash Earnings (cons. 3.7% vs 4.7%); Fed’s Logan speaks
– Thu 8-Oct: Weekly and Continuing Claims; Wholesale Inventories; 30-year reopening auction ($22bn); Fed’s Waller, Kashkari and Musalem speak
– Fri 9-Oct: University of Michigan Sentiment; Fed’s Collins speaks; Delta earnings
Also on the radar: ECB meeting minutes, the Brazilian general election this weekend, and, as always, US-Iran headlines.
Watch the auctions. After a weak 5-year auction two weeks ago and a 30-year yield at a 24-year high, the 10-year and 30-year reopenings on Wednesday and Thursday are a real test of demand at the long end.
Trader’s Note: A weaker jobs report should have been a gift for bonds and small caps, yet the 30-year still printed a 24-year high, France’s spread blew out, and fewer than a quarter of S&P 500 stocks are above their 50-day. When bad news on growth can’t bring yields down, the market is telling you the problem is term premium and fiscal risk, not just the Fed. Tech is doing all the heavy lifting; respect that trend, but with Wednesday’s FOMC Minutes and two long-end auctions on deck, keep an eye on the exit.
Stay Connected
Want to dive deeper or join the community?
📧 Book mentoring for Q4 2026: https://duponttrading.com/mentoring/
🎥 Access the 4×4 video series: https://duponttrading.com/4×4-course/
💬 Join the Discord: 30 channels of trading insights: https://discord.com/invite/Yf42SgAx7f
For any questions or to join our mentoring sessions, email us at Greg 📩 Contact: greg@duponttrading.com
Have a good Trading Week!
Sub Section Title Here
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur. Excepteur sint occaecat cupidatat non proident, sunt in culpa qui officia deserunt mollit anim id est laborum.
THIS POST

LEARN ONLINE TRADING TODAY. THE PROFESSIONAL WAY.
Let us solve the problem and confusion around trading and finance management, the right way.
ACCESS FREE LECTURESUBSCRIBE
TO OUR BLOG
To receive opinions, market research, and data analysis in the Financial Markets
ABOUT
DUPONT TRADING
As a Professional Trader/Portfolio Manager/Hedge Fund Manager for almost 20 years, I know that learning how to Trade/Invest is a non-ending learning curve. This adventure is extremely exciting but needs to be ridden carefully.
In January 2018 after receiving many requests, I decided to start my own mentoring activities.
In October 2019, I launched the 4×4 Video Series to help Investors profitably manage their portfolios. By sharing my ideas/experiences and offering education through the 4×4 Video Series, I hope I can help you becoming a better investor.
Students
Testimonials

K. (United Kingdom)
LEARN ONLINE TRADING TODAY. THE PROFESSIONAL WAY.
Let us solve the problem and confusion around trading and finance management, the right way.